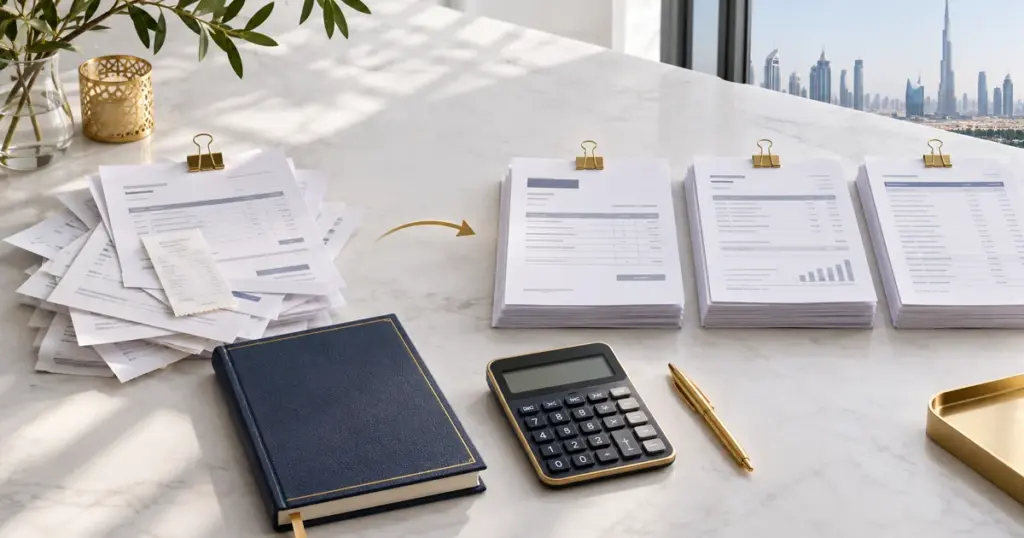
Reliable monthly bookkeeping gives a UAE business a clearer view of cash, margins, outstanding invoices and tax records. A consistent close also makes it easier to spot missing documents before they become a year-end problem. Use this checklist as a practical starting point and adapt it to your entity, industry and reporting needs.
1. Reconcile bank, card and payment accounts
Match every bank statement, company card and payment gateway to the accounting ledger. Investigate unmatched receipts, duplicate entries, bank charges and transfers between accounts. Reconciliation should end with a documented balance that agrees to the statement date, not a list of unexplained differences.
2. Review sales, receivables and supplier bills
Check that sales invoices are complete, correctly dated and linked to supporting contracts or delivery evidence. Review overdue customer balances and agree a follow-up owner. Match supplier bills to approvals and payment records, and flag disputed or duplicate invoices. This gives management a more realistic picture of expected cash in and cash out.
3. Keep tax and source records organized
File tax invoices, credit notes, contracts, expense evidence and customs or import documents in a consistent folder structure. The UAE Federal Tax Authority says Corporate Tax records must generally be retained for at least seven years after the relevant tax period, while VAT invoices are generally retained for at least five years. Confirm the rules that apply to your circumstances and keep records accessible.
VAT registration is based on taxable supplies and imports: the FTA currently describes mandatory registration at AED 375,000 and voluntary registration at AED 187,500, subject to the applicable tests. Monitor thresholds regularly and seek advice if your turnover is approaching them. See the FTA VAT registration guidance and our UAE tax services.
4. Check payroll, assets and inventory
Reconcile payroll totals to approved payroll reports and payment records. Update the fixed-asset register for additions, disposals and depreciation, and compare inventory records to stock counts where relevant. Document adjustments and approvals so another reviewer can understand what changed and why.
5. Close the month and review the numbers
Review the trial balance, profit and loss, balance sheet and cash-flow position. Compare results with budget and prior months, then investigate unusual movements. Record recurring accruals or prepayments consistently, and prepare a short management summary with key risks, upcoming payments and actions.
If several months of records are already outstanding, start with our UAE backlog accounting checklist to organise the evidence, understand the catch-up process and prepare for a scoped quotation.
PeterMorrison supports businesses with monthly, quarterly and annual accounting and bookkeeping. If your records need a broader review, explore our accounting and audit services. Learn about PeterMorrison, browse more practical guides in Insights, or contact our team to discuss a month-end process that fits your business.
This article is general information, not tax, legal or accounting advice for a specific situation. Requirements can change; confirm current rules with the relevant authority or a qualified adviser. See our Terms & Conditions.
Related guides: For a stronger month-end close, see our UAE audit preparation checklist and UAE company registration checklist.